How dealer floor plans actually work — and where they quietly eat your gross
How dealer floor plan financing works in practice: the credit line, daily interest, curtailments, audits, and the real per-car math.
Switching from another DMS? Compare DealerVLO to DealerCenter, Frazer, or Lot Wizard.
A floor plan is how most independent lots stock inventory without tying up $100,000 in cash: a lender fronts the purchase price at the auction, you pay interest by the day, and you pay the loan off when the car sells. Simple in concept. In practice, the mechanics (curtailments, audits, fees, the per-diem clock) are where dealers quietly give away gross without noticing. Here's how it actually works.
14-day free trial, then $29/mo · Cancel anytime
The basic machine
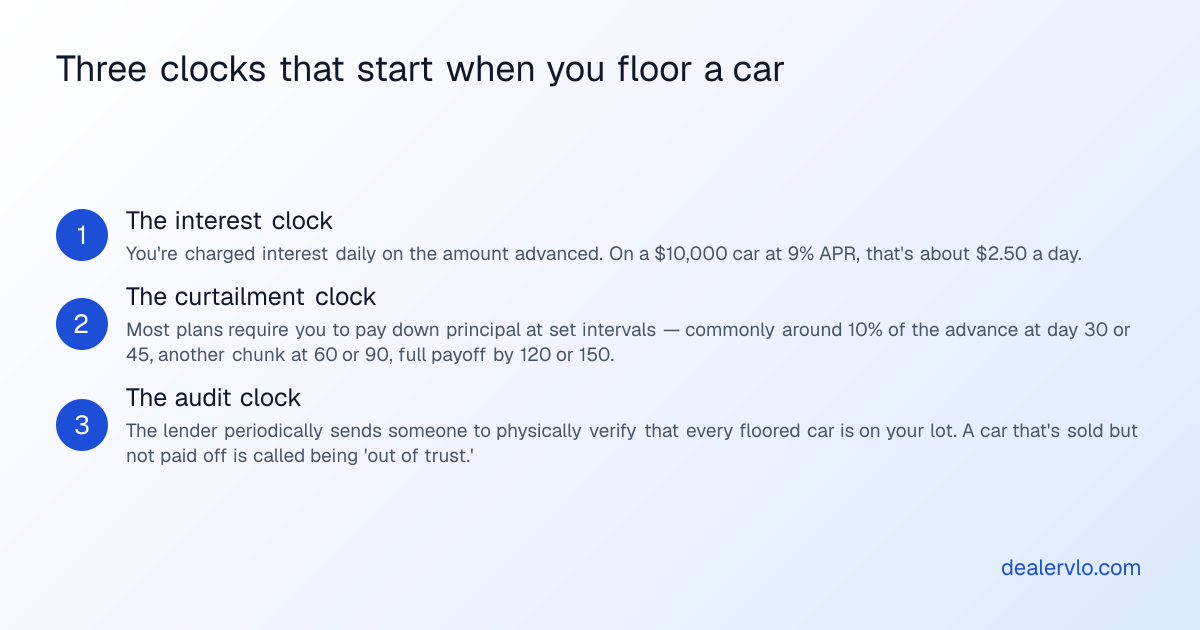
You get approved for a credit line (say $100,000) with a floor plan provider. At the auction, instead of paying cash, the purchase goes on the line. The lender holds the title. From that moment, three clocks start:
- The interest clock. You're charged interest daily on the amount advanced. On a $10,000 car at 9% APR, that's about $2.47 a day ($10,000 × 0.09 ÷ 365). Sounds small. It isn't; more below. (Nine percent is an example. Providers don't post standard rates; yours is quoted on your credit, time in business and volume.)
- The curtailment clock. Plans run in terms. AFC, for example, describes 30-, 45- or 60-day terms and says that if a car hasn't sold by the end of a term, the term "may be able to be extended for a fee and payment of a predetermined percentage of the loan's principal." That paydown is the curtailment. Term lengths and percentages differ by provider and are in your agreement. Miss one and you're in default territory.
- The audit clock. The lender periodically sends someone to physically verify that every floored car is on your lot. A car that's sold but not paid off, or worse, off the lot with no explanation, is called being "out of trust," and it's the fastest way to lose your line and, in bad cases, end up in litigation.
The real per-car math
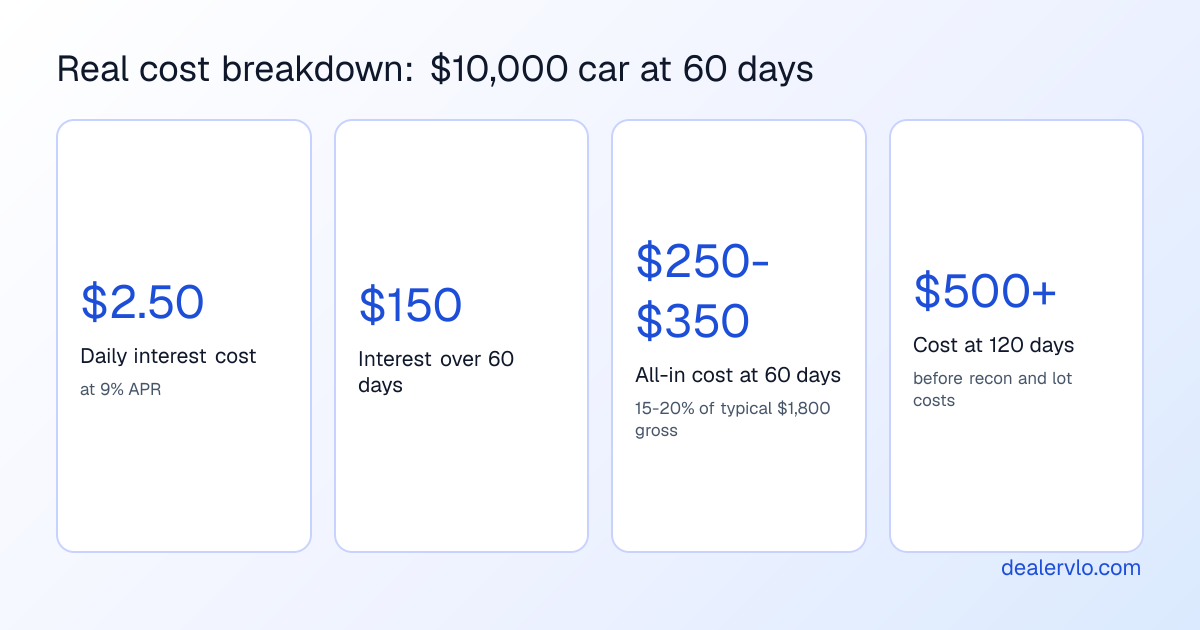
The APR is the number everyone quotes and only part of the real cost. The full stack on an example $10,000 unit:
- Interest: about $2.47 a day at 9%, or about $148 if the car sits 60 days
- Floor fee / origination: many plans charge a flat fee per floored unit. It's on your fee schedule; ask for it in writing
- Curtailment payments: not a cost, but a cash-flow hit: part of the principal due whether or not the car has sold
- Audit, extension and admin fees: small, recurring, and they add up across a full floor
Put an example $95 flat fee on top of the interest and you're at about $243 on a 60-day turn. If your target front gross is $1,800, that's about 13.5% of it, and that's a normal outcome, not a bad one. Let the same car drag to 120 days and interest alone is about $296, before any extension fee, recon or lot costs. Flat fees also hit fast turns hardest: that $95 on a car that sells in 30 days works out to about 11.6 points of APR ($95 ÷ $10,000 × 365 ÷ 30).

Run your own numbers in the floor plan calculator. It breaks out interest and fees by days held.
Estimate your daily floor-plan carrying cost per unit.
Open the Floor Plan CalculatorWhere dealers actually get hurt
Aging inventory on borrowed money. The floor plan converts "this car isn't selling" from a nagging feeling into a daily invoice. The discipline that follows: know your per-diem on every floored unit, and when a car hits day 45 without serious interest, reprice it hard. Holding out for full gross on a floored car is often just donating the difference to your lender.
Curtailments as a surprise. The first paydown comes due in cash at the end of the first term. Floor ten $10,000 cars in a good buying week, and even a 10% paydown on each is a five-figure bill a month or two later. Map curtailment dates when you buy, not when the notice arrives.
Sold-but-not-paid-off. You sell the car Tuesday, the buyer's bank funds Friday, and the floor plan expects payoff within days of sale. Sloppy back-office timing here is how honest dealers end up flagged out of trust. When the deal funds, the payoff goes out the same day.
Treating the line as profit. The line is inventory capacity, not income. Lots that use floor plan proceeds to cover payroll die suddenly and predictably.
14-day free trial, then $29/mo · Cancel anytime
Who the providers are
The big national names for independents are NextGear Capital (Cox Automotive), AFC (part of the OPENLANE family) and Westlake Flooring Services, plus bank lines for established dealers. None of the three posts a standard rate on its website; each quotes yours on your file. The fee structure and curtailment schedule matter as much as the rate. We compare what each one does publish in NextGear vs. AFC vs. Westlake, and what a Fed move does to a variable line in the September 2026 rate hike, per car.
The habits that keep a floor plan cheap
- Know the all-in daily cost per unit: interest plus amortized fees. Write it on the deal jacket mentally, if not literally.
- Buy for velocity. A floored car that turns in 25 days at $1,600 gross beats one that "should" make $2,400 and sits for 90. (More on that in buying wholesale the right way.)
- Reprice on a schedule, not on a feeling: day 30 and day 45, on the calendar.
- Reconcile weekly. Every floored VIN, its age, its curtailment date, its payoff status. Five minutes a week prevents the audit-day scramble (here is how to pass a floor plan audit step by step).
DealerVLO handles the inventory half of that reconcile. Every car shows its days in inventory, all-in cost with reconditioning, and margin, and cars past 60 days get an "aging, consider repricing" flag, so "what's aging and what's it costing me" is a screen, not a spreadsheet project. Curtailment dates and payoff status stay in your lender's portal; DealerVLO isn't a lender and doesn't track your line.
14-day free trial, then $29/mo · Cancel anytime