# The Common Ways Used-Car Dealers Lose Money (and How to Stop)
> Most lots don't lose money on one bad deal — they bleed it slowly through aged inventory, floor plan interest, uncounted recon, and weak F&I. Here's where it goes and how to plug it.
- Source: https://www.dealervlo.com/blog/how-used-car-dealers-lose-money
- Published: 2026-09-13
- Author: Chris Abouraad
- Tags: used car dealer profitability, aged inventory holding cost, floor plan interest, dealership cost control
---
Most lots don't go under because of one catastrophic deal. They bleed out slowly — a little on this aged unit, a little on that floor plan bill, a little on recon nobody added to the car's cost — until a year of "decent months" adds up to a business that isn't actually making money. The losses that kill you are the quiet ones, because you can't fix a leak you can't see.
I've made every one of these mistakes on my own lot. Here's where the money goes.
## Where do used-car dealers lose money?
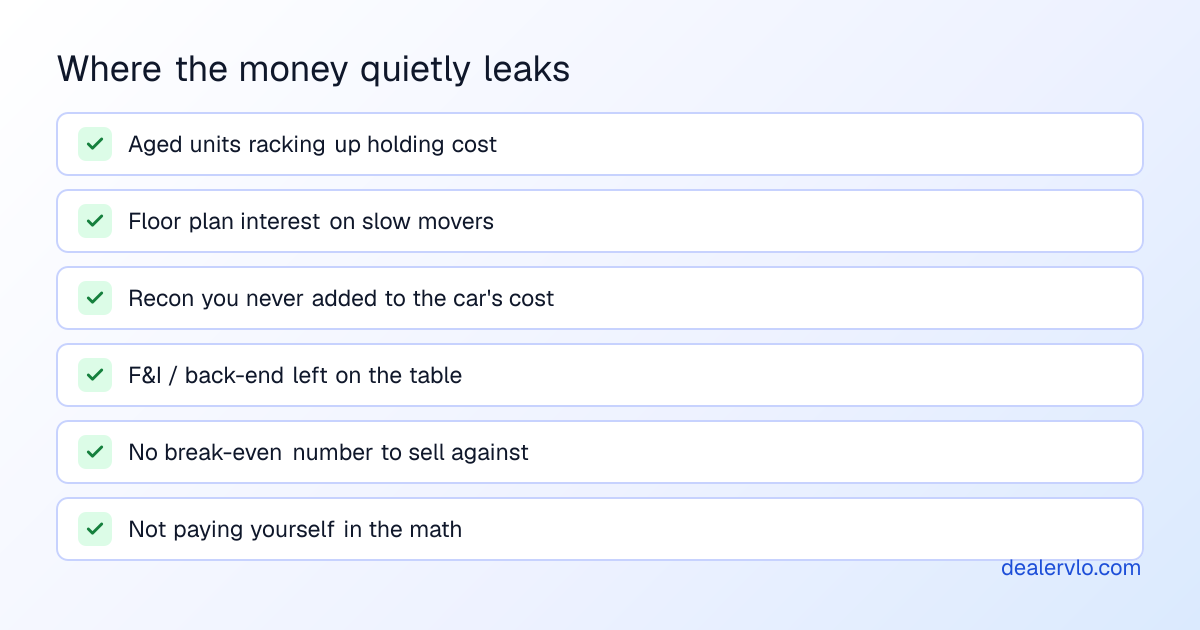
Notice what these have in common: none of them show up as a line item that says "loss." A car sitting too long, interest accruing in the background, recon that never made it into the cost, F&I you didn't present — each one just quietly makes your real profit smaller than the gross you're proud of.
## Leak #1: aged inventory
This is usually the biggest one. A car that sits doesn't just fail to sell — it charges you rent the whole time it's there. Floor plan interest if it's floored, insurance and lot overhead it has to carry, and depreciation as the market moves past it. At even a modest holding cost, the meter runs fast:
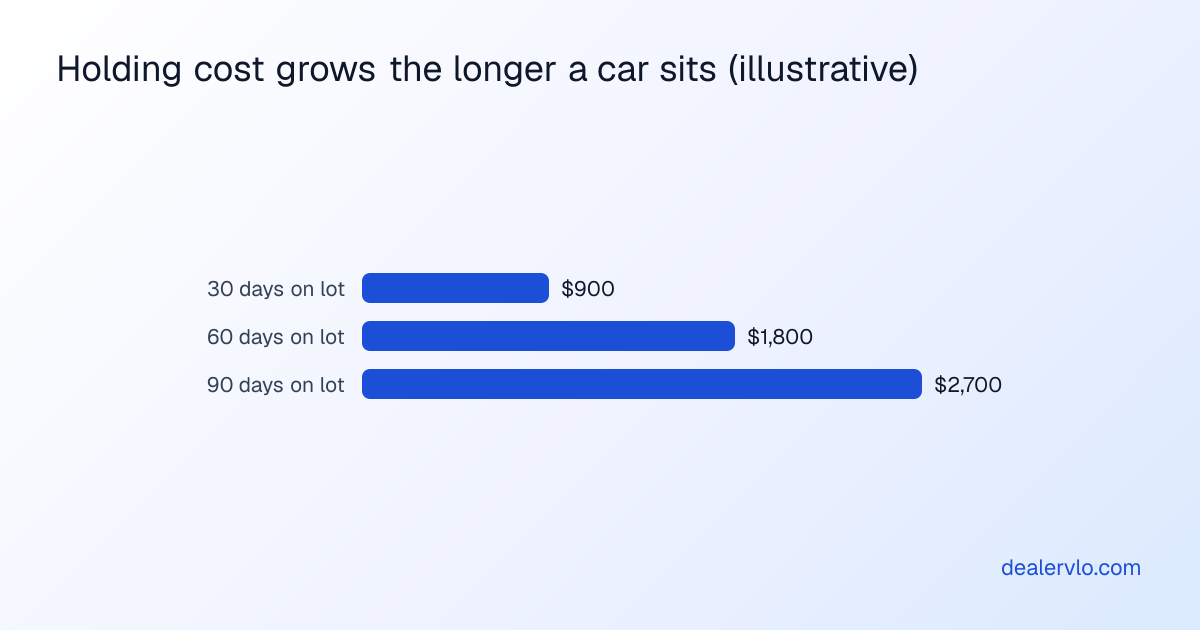
*(Illustrative, at an assumed ~$30/day in total holding cost — your real number depends on your floor plan rate, insurance, and lot cost. Run yours on the [holding-cost calculator](/tools/holding-cost-calculator).)*
The unit you could have wholesaled in week three for a small, clean loss becomes a bigger loss by week twelve — plus everything it cost you to hold it in between. Most dealers lose more to slow turn than to any single bad buy. That's why [days-in-stock and turn rate](/blog/inventory-turn-rate-used-car-dealers) matter as much as gross.
## Leak #2: floor plan interest you don't watch
If you [floor your inventory](/blog/how-dealer-floor-plans-work), interest is charged per day on every unit — not per sale. A few aged cars each carrying an extra 60–90 days of interest can quietly erase the profit from your best deals of the month. The interest is a real expense, and when you track it as one, two things happen: your net profit gets honest, and the cost of aging becomes visible right when you're deciding whether to move a slow unit.
That's exactly what a real P&L surfaces — the floor plan line sitting there in your operating expenses, and the aging showing up in your sales report:
## Leaks #3–#5: recon, F&I, and paying yourself
- **Uncounted recon.** If you spend $1,200 making a car ready and never add it to the car's cost, your gross looks $1,200 better than it is. You're not richer — you just measured wrong. Put [real recon into every car's cost](/blog/used-car-reconditioning-cost-budget).
- **Back-end left on the table.** F&I income you didn't present is money you never collected. Not every customer takes a warranty, but the ones who would can't if you never offer it.
- **Not paying yourself.** If your own draw isn't in the overhead math, a "profitable" month is really you working for free. Pay yourself in the numbers, then look at net.
## How do you stop losing money on a car lot?
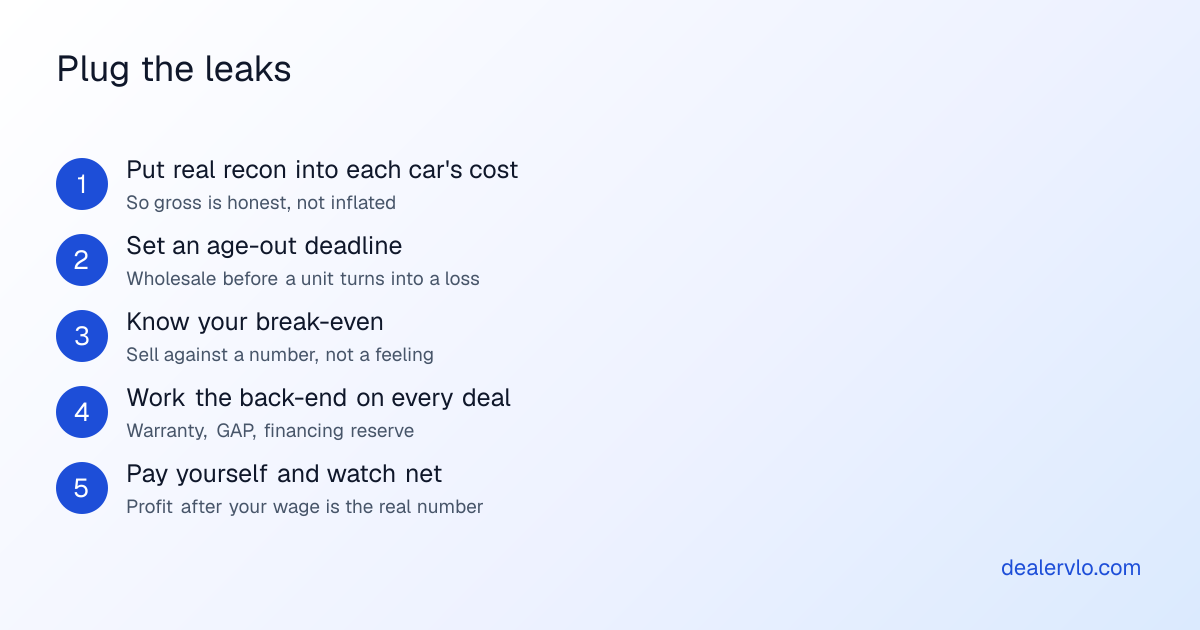
None of this requires a turnaround consultant. It requires seeing the leaks — which means tracking real cost on every car and looking at real net profit, not gross. That's the whole reason a [profit and loss that separates gross from net](/blog/used-car-dealership-gross-vs-net-profit) is worth having: it turns invisible bleeding into a number you can act on.
## Frequently asked questions
**What is the biggest way used-car dealers lose money?**
Aged inventory. A car that sits costs you every day — floor plan interest, insurance, lot overhead, and depreciation. Most dealers lose more to slow turn than to any single bad buy, because the bleed is invisible until you add it up.
**How do dealers lose money without realizing it?**
Through losses that never show up as a line item: uncounted recon that inflates gross, floor plan interest accruing quietly, F&I income never presented, and not paying themselves a wage. You can't fix a leak you can't see, so the fix starts with tracking real cost and real net.
**Does floor plan interest really cost that much?**
It adds up faster than expected because it's charged per day on every floored unit. A few aged cars carrying an extra 60–90 days of interest can erase the profit from your best deals. Tracking it makes the cost of aging visible.
**How can I tell if my lot is losing money?**
Build a P&L for a recent period: revenue minus cost of cars sold equals gross; minus operating expenses equals net. Negative after paying yourself means a busy month was a losing one. Most can't answer quickly because they track gross but never subtract overhead.
**How do I stop losing money on aged inventory?**
Set an age-out deadline before you buy and hold to it. The loss you avoid isn't just the wholesale discount — it's the holding cost and depreciation you stop paying the moment the car leaves.
## Bottom line
The money doesn't usually leave in one dramatic loss. It leaks — through aged units, floor plan interest, uncounted recon, and back-end you didn't work. Track real cost and watch real net, and the leaks stop being invisible. DealerVLO puts your deal gross and your overhead in one place so net profit — and where it's slipping — is one click away. [Start a free trial](/signup).
---
## FAQ
### What is the biggest way used-car dealers lose money?
Aged inventory is usually the biggest quiet leak. A car that sits doesn't just fail to sell — it costs you every day it's on the lot: floor plan interest if it's floored, insurance and lot overhead it has to carry, and steady depreciation as the market moves past it. A unit you could have wholesaled in week three for a small loss can turn into a bigger loss by week twelve, plus all the holding cost in between. Most dealers lose more to slow turn than to any single bad buy, because the bleed is invisible until you add it up.
### How do dealers lose money without realizing it?
The losses that hurt most are the ones that never show up as a line item. Recon you paid for but never added to the car's cost makes your gross look better than it is. Floor plan interest accrues quietly in the background. F&I income you didn't present is money you simply never collected. And if you don't pay yourself a wage in the math, a 'profitable' month is really just you working for free. None of these feel like losing money in the moment, which is exactly why they add up — you can't fix a leak you can't see, so the fix starts with tracking real cost and real net profit.
### Does floor plan interest really cost that much?
It adds up faster than most dealers expect, because it's charged per day on every floored unit, not per sale. A handful of aged cars each carrying interest for an extra 60 or 90 days can quietly erase the profit from your best deals of the month. The interest itself is only part of it — the bigger cost is what the slow turn signals: capital and a lot spot tied up in a car that isn't moving. Tracking the interest as a real expense makes the cost of aging visible and gives you the push to wholesale before a unit turns into a loss.
### How can I tell if my used-car lot is losing money?
Build a real profit and loss for a recent period: total revenue, minus the cost of the cars you sold (acquisition plus recon plus F&I cost), equals gross profit; minus your operating expenses, equals net. If net is negative after you've paid yourself, a busy month was actually a losing one. The reason most dealers can't answer this quickly is that they track gross but never subtract real overhead — so software that already knows your deal gross and lets you record expenses can show net at a glance and surface exactly where it's leaking.
### How do I stop losing money on aged inventory?
Set an age-out deadline before you buy, not after. Decide the day you bring a car in that if it isn't sold by, say, 45 or 60 days, it goes to wholesale — and hold yourself to it. The discipline works because the loss you're avoiding isn't just the discount you'll take; it's the additional holding cost and depreciation you stop paying the moment the car leaves. Watching days-in-stock and holding cost per unit turns 'I'll move it eventually' into a decision with a number attached.